Could a single spark on a remote Permian Basin job site end a decade of hard work because your policy lacks "Completed Operations" coverage? You've likely felt the frustration of rising premiums and the complexity of Master Service Agreements (MSAs) that demand coverage limits far beyond the Texas state minimums. It's difficult to find the balance between staying compliant with major operators and keeping your overhead manageable. This 2026 guide reveals how to secure general liability insurance for welders in Midland that actually meets these high-stakes requirements without overpaying.
We'll examine the specific coverage gaps found in standard policies, explain how to navigate the $5 million to $10 million limits often required in the oilfield, and show you how to get proof of insurance delivered fast enough to keep your crews on the move. By the end, you'll have a clear roadmap for protecting your business while meeting the rigorous demands of the Midland energy corridor. Our focus is on providing the technical clarity you need to make informed decisions for your operations and ensure long term stability for your welding business.
Operating a welding business in West Texas involves managing constant physical and financial exposure. At its core, Commercial General Liability (CGL) is designed to protect your company from third-party claims involving bodily injury or property damage. This policy covers the legal fees and settlement costs associated with accidents that occur during the course of your work, whether you're in a dedicated shop or at a remote drilling site. For those seeking general liability insurance for welders in Midland, this coverage isn't just a line item; it's a prerequisite for entering any professional job site.
Texas contractors often find that securing commercial permits or bidding on municipal projects requires proof of active coverage. Beyond the legalities, the financial reality is stark. A single spark resulting in a structure fire or an industrial explosion can lead to a lawsuit that exceeds the annual revenue of a small welding operation. Without professional risk transfer, one operational error can lead to permanent bankruptcy. Most independent agencies in the region emphasize that this coverage is the bare minimum for business continuity.
To better understand the mechanics of this coverage, watch this helpful video:
A critical feature of a robust policy is the "Duty to Defend" clause. This provision requires the insurer to provide a legal defense for covered claims, even if the allegations are eventually proven groundless. This is vital because the cost of legal representation alone can cripple a business before a case even reaches trial. General liability insurance for welders in Midland serves as the foundational shield against operational accidents. It provides the stability needed to build out a broader portfolio including workers' compensation and commercial auto insurance, ensuring that your business remains resilient against unforeseen events.
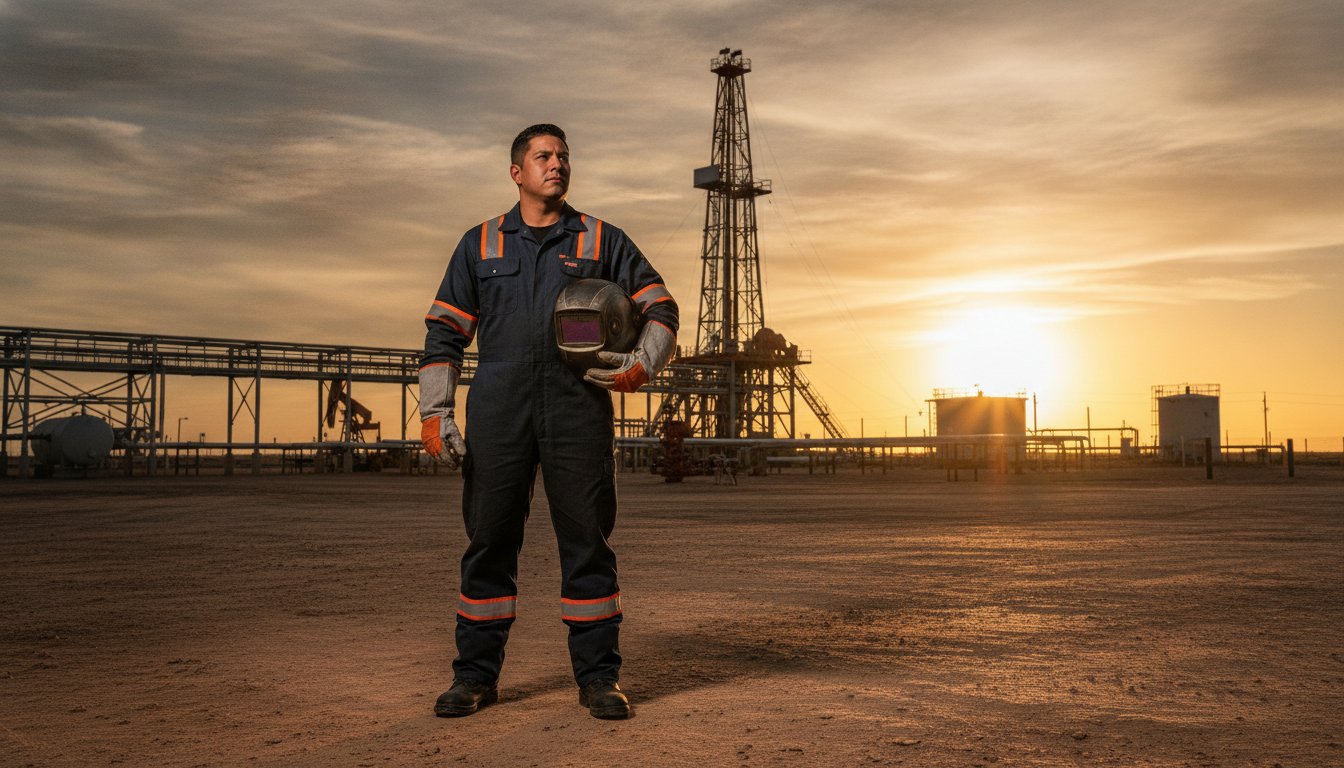
The Permian Basin presents a unique set of challenges that standard business policies often ignore. Hot work in oilfield environments carries magnified risks due to the presence of flammable gases and high-pressure equipment. Midland's specific climate, characterized by high winds and prolonged dry periods, turns routine welding into a high-risk activity where sparks can travel significant distances. Specialized welding hazards require policies that account for these environmental variables. A generic policy might contain exclusions for specific industrial sites, leaving you vulnerable during the most critical phases of a project. Professional risk management must account for these regional factors to ensure comprehensive protection.
A comprehensive policy for general liability insurance for welders in Midland consists of several distinct layers of protection. While the primary objective is to mitigate the financial impact of accidents, each component addresses a specific type of risk. Most policies start with Bodily Injury Liability, which covers medical expenses, loss of income, and legal settlements if a non-employee is injured on your premises or at a job site. For instance, if a site supervisor trips over your welding leads, this coverage manages the resulting claim. Property Damage coverage is equally vital, protecting you if your work causes physical damage to a client's facility, equipment, or surrounding structures. Adhering to OSHA safety standards is the first step in risk mitigation, but insurance provides the necessary financial backstop when accidents occur despite your best efforts.
Other technical components include Personal and Advertising Injury, which handles non-physical claims such as libel, slander, or copyright infringement in your marketing materials. Medical Payments coverage provides a smaller, secondary limit for immediate medical costs regardless of fault. This can often resolve minor incidents quickly before they escalate into full-scale litigation. Understanding these building blocks allows you to build a resilient defense for your operations. If you're unsure which specific limits your contract requires, you can consult with an independent agent to review your current policy against industry benchmarks.
Your liability doesn't end when you pack up the truck and leave the job site. Products and Completed Operations coverage is a critical component that protects your business from claims arising after the project is finished. In the welding industry, structural failures or weld defects might not manifest for months or even years. If a pipe weld fails six months after installation and causes a significant environmental leak, your Completed Operations coverage is what responds to the claim. It's essential to ensure your policy doesn't include a "sunset clause" or restrictive retroactive dates that leave you exposed for past work. This long-term protection ensures that the work you do today doesn't become a financial burden for your business tomorrow.
When selecting general liability insurance for welders in Midland, you'll typically encounter a $1 million per-occurrence limit and a $2 million aggregate limit. The per-occurrence limit is the maximum the insurer will pay for a single claim, while the aggregate is the total amount available during the entire policy period. Many Permian Basin operators now require higher limits, sometimes necessitating an umbrella policy to meet Master Service Agreement (MSA) standards. Balancing these limits with your deductible is a strategic financial decision. A higher deductible can lower your annual premium but requires you to have more cash on hand if a claim arises. Professional risk management involves finding the equilibrium where your premiums are affordable and your out-of-pocket exposure remains manageable.
Your operational footprint directly dictates your risk exposure and premium structure. A welder operating out of a fixed facility in a Midland industrial park faces different liabilities than a rig welder traversing the Permian Basin. While both require general liability insurance for welders in Midland, the specific endorsements needed to close coverage gaps vary significantly. Shop owners primarily focus on premises liability, whereas mobile contractors must account for the risks inherent in working on third-party sites and public roadways. Identifying your primary operation type is the first step in avoiding costly gaps in your protection.
Mobile operations in West Texas carry unique exposures that a standard liability policy may not fully address. When you're performing roadside repairs on Highway 191 or I-20, the risk of third-party property damage or bodily injury increases due to traffic and uncontrolled environments. It's crucial to understand the intersection between your Commercial Auto and General Liability policies. If a fire starts from a spark while working on a client's rig, the specific language in your policy determines which coverage responds. Often, you need an "Inland Marine" endorsement or an equipment floater to protect your welder-generator and specialized tools while they're in transit. Following American Welding Society safety standards helps demonstrate a commitment to risk mitigation, which can be a favorable factor when underwriters evaluate your mobile rig's profile.
Shop-based welding shifts the focus toward premises liability and fire legal liability. If you lease a shop space in Midland, your landlord likely requires specific coverage for damage to the rented premises. You're also responsible for the safety of anyone entering your facility, including delivery drivers or inspectors. Managing foot traffic and non-employee safety is a constant operational requirement in a fabrication environment. Additionally, fabrication shops often face higher product liability risks. If you manufacture structural components that are later sold and installed by third parties, you must ensure your policy covers the liability associated with those specific products. Premiums for shop-based operations are often more stable because the environment is controlled, unlike the unpredictable nature of field work. By isolating these risks, you can secure general liability insurance for welders in Midland that reflects the actual reality of your daily work.
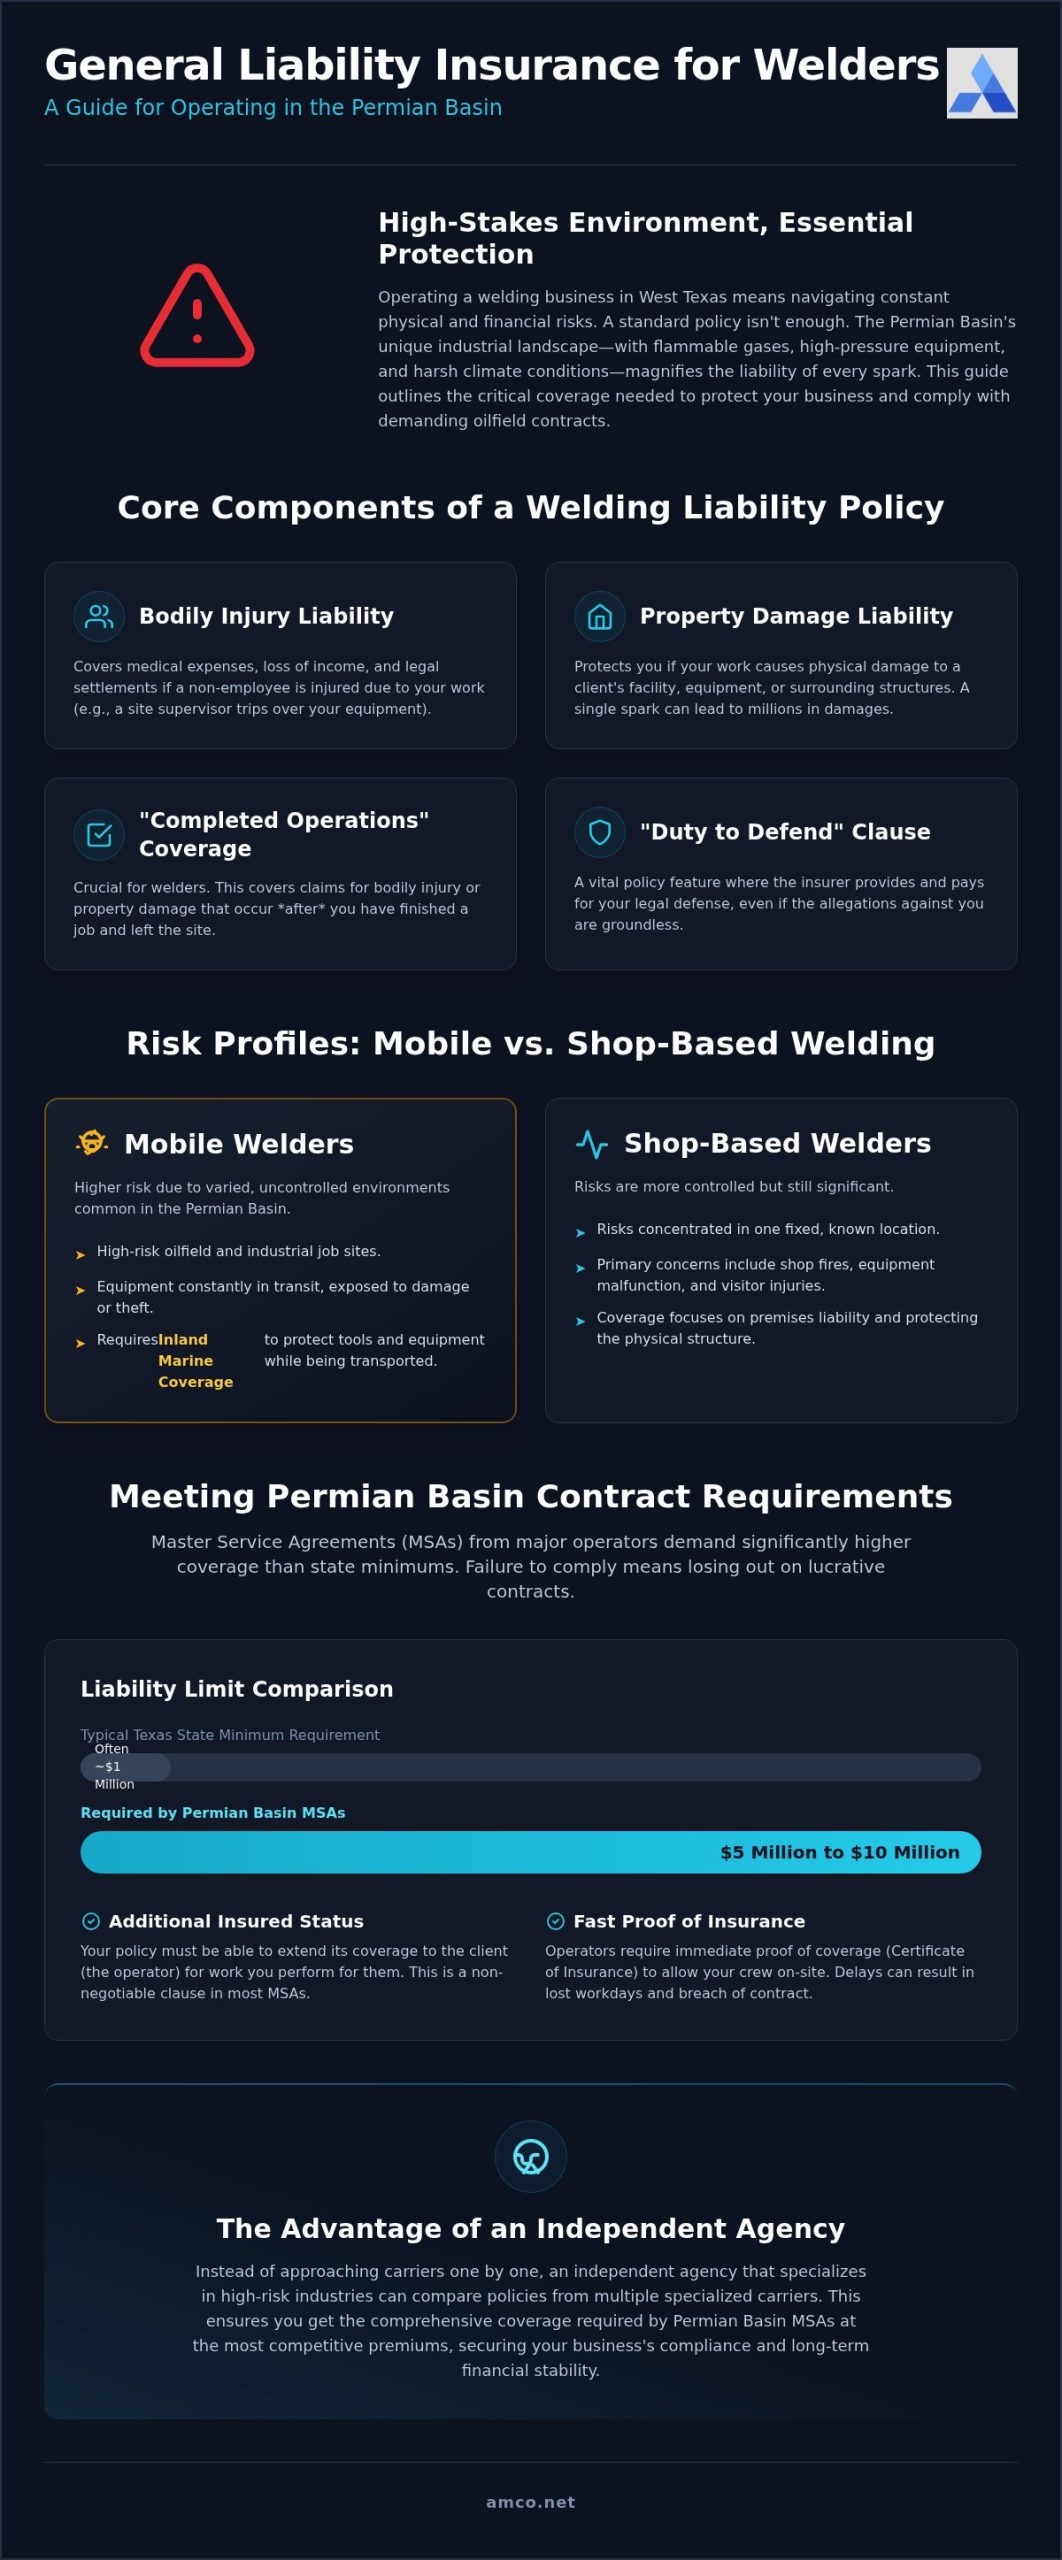
Working for major operators in the Midland energy sector requires more than just technical welding proficiency; it demands a sophisticated approach to risk transfer. Most projects in the Permian Basin are governed by Master Service Agreements (MSAs). These legal contracts dictate the exact specifications for your general liability insurance for welders in Midland, often requiring limits and clauses that go far beyond standard small business policies. Operators use these agreements to ensure that the financial burden of an accident remains with the contractor. If your policy isn't perfectly aligned with the MSA, you'll likely be barred from the job site before you can strike an arc.
A standard requirement in these contracts is the "Additional Insured" endorsement. This provision grants the operator protection under your policy for claims resulting from your operations. Along with this, you'll almost certainly encounter a "Waiver of Subrogation." This clause prevents your insurance carrier from seeking recovery from the operator after paying a claim, even if the operator's negligence contributed to the incident. To ensure your policy pays out first without involving the operator's own coverage, contracts also mandate "Primary and Non-Contributory" language. These technical details are non-negotiable in the oil patch.
Reviewing the insurance section of an MSA before signing is a critical step in your business operations. Generic policies often contain "gotchas" or exclusions for specific industrial activities that oilfield contracts expressly require. For example, some policies might exclude work on high-pressure vessels or have restrictive height and depth limitations. If your business utilizes a fleet of heavy rigs to move fabrication units across the state, you may also need to coordinate your liability with Commercial Trucking Insurance in Houston or other regional logistics hubs. Ensuring every piece of your insurance portfolio talks to each other prevents expensive coverage overlaps or dangerous gaps.
In the fast-moving Midland economy, speed is a competitive advantage. When an operator calls for an emergency repair, you can't afford to wait days for your agent to process a Certificate of Insurance (COI). You need a partner that understands the urgency of the oilfield and can deliver accurate certificates in minutes. Managing multiple COIs for various clients requires an organized system and an agency that stays on top of evolving operator demands. If you're struggling to meet the rigorous insurance standards of a new contract, you can request a professional policy review to ensure you're fully compliant and ready to work.
AMCO.NET LLC has provided dedicated support to Texas contractors since 1987; this extensive history allows for a deep understanding of the unique risks present in the Permian Basin. As an independent agency, AMCO.NET LLC doesn't represent just one carrier. Instead, we shop the market to find specialized general liability insurance for welders in Midland that accounts for high-risk industrial environments. This independent status allows for multi-carrier price comparisons, ensuring you receive a policy tailored to the specific technical demands of your operation without unnecessary overhead.
We understand the operational pace of the local energy sector. Our team provides technical guidance on general liability insurance for welders in Midland to ensure your contracts remain active and compliant with evolving operator standards. This local presence in Midland and Odessa ensures you receive personalized service from professionals who understand regional climate factors and industrial landscapes. AMCO.NET LLC prioritizes efficiency, offering digital policy management and fast quote turnaround times to help you stay focused on production and site safety.
Protecting a welding business requires a comprehensive approach that often extends beyond general liability. AMCO.NET LLC provides expertise in coordinating both General Liability and Workers Compensation insurance to ensure full protection for your workforce and assets. If you're searching for a reliable Insurance Company Near Me, our local team is ready to provide the specialized support required in West Texas. Our systems are built to help you scale your business, whether you're currently operating a solo rig or managing a full fabrication crew with multiple vehicles.
Securing the right coverage doesn't have to be a bottleneck for your operations. The streamlined intake process at AMCO.NET LLC allows for simple online submissions or direct phone-based consultations with an experienced agent. To expedite your quote, have your projected annual revenue, payroll estimates, and total equipment values ready for review. This data allows us to present the most accurate risk profile to our carrier partners, resulting in more competitive premiums. You can get a fast welding insurance quote from AMCO.NET LLC today and ensure your business is fully protected according to the latest 2026 Permian Basin standards.
Securing the right general liability insurance for welders in Midland is about more than just checking a box for a contract; it's about ensuring the long-term continuity of your business in a high-stakes environment. By addressing the specific requirements of Master Service Agreements and closing the gap on completed operations, you position your company as a reliable partner for major operators. Whether you manage a mobile rig on the highways or a fabrication shop in an industrial park, your coverage must reflect the actual technical risks you face every day.
AMCO.NET LLC has been serving Texas contractors since 1987, leveraging a deep understanding of the local energy sector to provide specialized solutions. We work with A+ rated carriers to deliver the stability your business deserves, backed by the ability to provide instant COI delivery when jobs move fast. Don't let insurance hurdles delay your next project. Take the next step toward professional risk management today. Get Your Fast Midland Welding Insurance Quote and keep your crews working with confidence.
Your premium is determined by several operational factors including your annual gross revenue, total payroll, and whether you operate a mobile rig or a fixed shop. High-risk oilfield work typically commands different rates than residential fabrication. As an independent agency, AMCO.NET LLC shops multiple specialized carriers to find competitive pricing that matches your specific risk profile. This market comparison ensures you don't overpay for the coverage required by Permian Basin operators while maintaining necessary protection.
Standard general liability insurance for welders in Midland doesn't protect your physical assets like welding machines, generators, or hand tools. It's strictly designed to cover third-party claims for bodily injury or property damage. To protect your gear from theft or damage during transit, you should add an Inland Marine endorsement or a separate Commercial Property Insurance policy. These additions ensure your specialized equipment is covered while moving between various Midland job sites and remote drilling locations.
This coverage protects your business against claims arising from work you've already finished and handed over to the client. In the welding industry, structural or pipe weld failures might not occur until months after the project is complete. Without this specific endorsement, you could be held personally liable for damages that manifest after you've left the site. It's a critical component for maintaining long-term financial stability and professional credibility in the industrial and energy sectors.
Speed is essential in the Midland oil patch, and AMCO.NET LLC prioritizes rapid response times for contractors. While the underwriting process varies by carrier, we often deliver certificates of insurance the same day you're approved. Having your financial data and equipment values ready helps expedite the process. Our digital management systems are built to ensure you can provide proof of coverage to site supervisors immediately, preventing any delays in starting your next project or mobilization.
Most Midland oilfield operators mandate a comprehensive insurance portfolio that extends far beyond basic liability. Master Service Agreements (MSAs) frequently require Commercial Auto Insurance, Workers Compensation, and often an Umbrella policy to reach limits of $5 million or $10 million. You'll also likely need specific endorsements like Waiver of Subrogation and Primary and Non-Contributory language. We help you review these complex contracts to ensure every technical requirement is met before you mobilize your crew.
Underwriters generally view mobile welding as a higher risk profile due to the lack of a controlled environment. When you're working on-site in the Permian Basin, you face unpredictable variables like high winds, flammable gases, and third-party foot traffic. Roadside repairs on busy corridors like I-20 also introduce unique transit liabilities. Shop-based operations are often more predictable, which can influence the structure of your general liability insurance for welders in Midland and its associated premiums.
Working as a subcontractor doesn't exempt you from needing your own insurance; in fact, it often increases the documentation required. The general contractor will likely require you to name them as an "Additional Insured" on your policy. This ensures that your insurance pays first if an accident occurs due to your specific work. Maintaining your own coverage protects your business assets and ensures you remain eligible for lucrative subcontracts with larger Midland engineering and oilfield service firms.
Most commercial policies written for Texas contractors provide coverage throughout the state, including neighboring cities like Odessa or larger hubs like Houston. However, it's vital to verify the "Territorial Limits" section of your specific policy. If your operations take you across state lines or into specialized offshore environments, you may need a specific endorsement. We ensure your policy remains active and compliant wherever your welding rig travels within the Permian Basin and the broader Texas region.